Argentina country risk rose to 610 points after reaching 628, as bonds fell and analysts debated peso depreciation, reserves and exchange controls before 2027.
Related: Marcha de la Bronca Argentina: 5 Powerful Demands Against Milei’s Harsh Cuts
Argentina Country Risk Surpasses 600 Points Amid Currency Debate
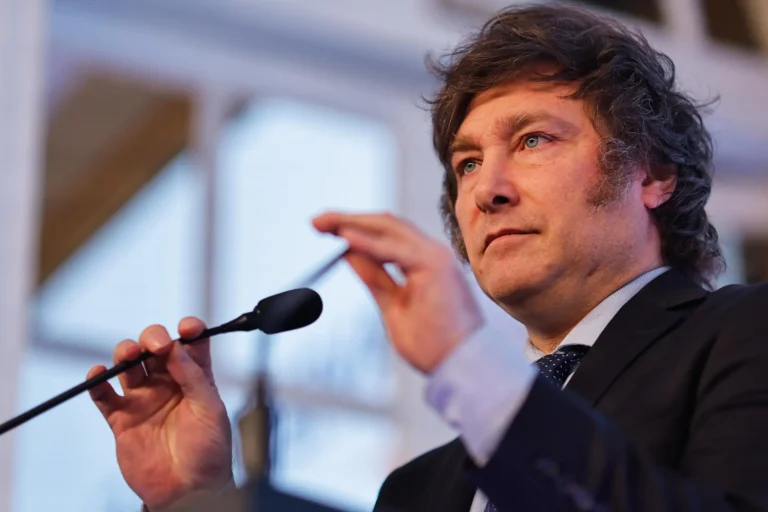
Argentina country risk climbed above 600 basis points on Friday, reaching 610 points after hitting an intraday high of 628, as investors sold Argentine sovereign bonds and renewed debate over President Javier Milei’s exchange-rate strategy.
The increase marked the indicator’s highest level in approximately five months and reflected growing concern over Argentina’s ability to regain stable access to international credit markets.
The country-risk index measures the additional interest rate investors demand to hold Argentine dollar-denominated debt compared with U.S. Treasury bonds.
When the indicator rises, it becomes more expensive for the government and private companies to borrow abroad. It also signals that investors perceive a greater possibility of financial stress, debt restructuring, currency instability, or political disruption.
The latest deterioration occurred alongside a new decline in Argentine sovereign bonds. The fall in bond prices pushed yields higher and weakened the government’s effort to present the country as a successful example of fiscal adjustment and market stabilization.
Argentina’s S&P Merval index also recorded its fifth consecutive session of losses when measured in international currency.
The market downturn came during a difficult international environment. The yield on the 10-year U.S. Treasury bond rose to approximately 5.15 percent, increasing the cost of capital for emerging markets.
When U.S. Treasury yields rise, investors often move money away from riskier assets and toward dollar-denominated instruments considered safer. That shift places additional pressure on countries such as Argentina, which remain dependent on foreign financing and investor confidence.
The increase in Argentina country risk therefore reflects both domestic uncertainty and global financial conditions.
The Milei administration has based its economic strategy on fiscal surplus, the restoration of investor confidence, and an eventual return to international credit markets.
However, the recent behavior of sovereign bonds demonstrates that balanced public accounts alone may not be enough to guarantee financial stability.
Investors are also evaluating the exchange-rate regime, the level of central-bank reserves, inflation expectations, external debt repayments, political tensions, and the government’s ability to maintain support ahead of the 2027 presidential election.[riotimesonline][riotimesonline]
The rise in Argentina country risk shows that markets remain unconvinced that the current stabilization strategy has resolved the country’s structural vulnerabilities.
Argentina Country Risk and the Peso Exchange-Rate Debate
Read about Gita Gopinath’s recommendations on Argentina’s peso and foreign reserves.
The rise in Argentina country risk has intensified disagreement over how the government should manage the peso.
Some economists and financial institutions argue that the national currency is overvalued and should be allowed to depreciate further. They say a more flexible exchange rate would improve competitiveness, reduce pressure on imports, and help rebuild foreign-exchange reserves.
Others warn that a sharp depreciation could reignite inflation, reduce household purchasing power, and weaken the credibility gained through fiscal discipline.
The debate is particularly sensitive because Argentina has experienced repeated currency crises, devaluations, capital controls, and inflationary episodes.
Former International Monetary Fund deputy managing director Gita Gopinath said Argentina should allow the peso to adjust more and accelerate the accumulation of foreign-exchange reserves.
“The Argentine peso needs to adjust more and should be allowed to depreciate more than it is currently,” Gopinath said in an interview with economist Tyler Cowen.
She argued that Argentina should buy dollars more rapidly to strengthen its reserve position ahead of the 2027 presidential election.
Gopinath said the government could allow more movement within the existing exchange-rate band without abandoning its objective of eventually operating with a floating currency.
She also warned that Argentina’s history of monetary instability makes it especially important for the central bank to accumulate reserves at a much faster pace.
The former IMF official’s comments were interpreted as criticism of the government’s reluctance to allow a stronger adjustment of the peso.
Her argument is that maintaining an exchange rate that is too strong can create pressure on reserves and make future corrections more disruptive.
The government’s current framework includes an exchange-rate band intended to allow gradual movement rather than a fixed peg. Officials say the system provides stability and helps anchor inflation expectations.
Financial-sector critics respond that the exchange rate may not reflect the country’s underlying inflation, productivity, and external financing conditions.
The disagreement has also divided investment banks and international funds.
Facundo Gómez Minujín, JP Morgan’s chief executive for the region, said foreign investment funds remain cautious and are waiting for greater clarity before committing significant capital to Argentina.
He projected that exchange controls could remain in place until after the 2027 presidential election, delaying a complete liberalization of the foreign-exchange market.
The statement suggests that international investors do not expect the government to eliminate restrictions quickly, despite its commitment to deregulation.
Exchange controls limit access to foreign currency and regulate capital movements. The government has gradually relaxed some restrictions, but it has maintained controls to prevent a sudden loss of reserves and speculative pressure on the peso.
The decision to maintain controls may protect the central bank in the short term, but it also creates uncertainty for companies, importers, investors, and savers.
Businesses need to know whether they can access dollars, pay foreign debts, import equipment, and transfer profits abroad.
Investors also want clarity over whether future administrations will maintain the same exchange-rate rules.
The debate over Argentina country risk therefore involves more than the price of the dollar. It concerns the credibility of the government’s broader economic program.
Sovereign Bonds, Reserves, and Investor Confidence
See Allianz’s Argentina country-risk assessment and reserve outlook.
The recent rise in Argentina country risk comes as the government attempts to restore access to global debt markets.
The administration says fiscal surpluses and lower inflation will eventually allow Argentina to borrow at sustainable rates and refinance its obligations.
But investors remain concerned about foreign reserves and future debt payments. Argentina faces large external obligations, while the central bank’s reserve position remains relatively limited compared with the country’s financing needs.
The IMF is expected to resume principal repayments in September 2026, increasing pressure on Argentina’s external accounts.
Higher debt payments could force the government to accelerate reserve accumulation, seek additional financing, or adjust its economic policy.
The government’s supporters argue that fiscal discipline will gradually reduce risk and attract capital. They say markets need time to recognize that Argentina has changed its economic direction.
Critics respond that adjustment without growth, investment, and reserve accumulation can leave the economy vulnerable to external shocks.
The fall in sovereign bonds indicates that investors are not only judging current fiscal performance. They are also assessing whether Argentina can maintain its policies during an election year.
Political uncertainty may increase if the government faces opposition from provincial leaders, trade unions, social organizations, or voters affected by reduced public spending.
The government has reduced subsidies, public-sector employment, transfers to provinces, and some social expenditures. Officials say the cuts are necessary to end monetary financing of the deficit.
Opponents argue that the adjustment has increased poverty, weakened public services, and damaged domestic demand.
The social consequences of the program may influence the credibility of future reforms. If public dissatisfaction grows, investors could fear that a future government will reverse the policies or introduce new controls.
Argentina country risk also depends on whether the country can expand exports and generate sufficient foreign currency.
The administration is seeking investment in energy, mining, agriculture, and infrastructure. The Vaca Muerta shale formation, lithium production, and agricultural exports are central to its strategy.
Greater export revenue could help the central bank build reserves and reduce dependence on external borrowing.
However, investment projects require time, infrastructure, legal certainty, and access to financing. Investors may delay decisions if they believe the exchange rate is misaligned or if they expect political changes in 2027.
The government therefore faces a difficult balance. It wants to attract investment while avoiding a currency adjustment that could undermine its anti-inflation strategy.
A weaker peso could improve export competitiveness but also raise the local cost of imported goods, energy, machinery, and debt payments.
A stronger peso can help reduce inflation in the short term but may weaken exporters and increase pressure on reserves.
The debate over the exchange rate has become a test of the government’s economic priorities. It must decide whether to protect nominal stability or accept more depreciation to strengthen the external position.
The behavior of Argentina country risk suggests that investors are demanding a clearer answer.
Geopolitical Context: Argentina, the IMF, and Global Finance
The rise in Argentina country risk has implications beyond domestic economic policy because Argentina remains one of the largest debtors to the IMF and an important economy in South America.
The country’s relationship with the IMF influences access to international financing, investor confidence, and the government’s ability to manage external payments.
Milei has presented his administration as aligned with market reform and fiscal discipline. That position has attracted attention from international investors and conservative governments that view Argentina as a test case for aggressive deregulation.
At the same time, the country remains vulnerable to global interest rates, commodity prices, external demand, and geopolitical shifts.
Higher U.S. Treasury yields have increased financing costs across emerging markets. If global rates remain elevated, Argentina may face a longer period of restricted access to credit.
The country must also navigate relations with the United States, China, Brazil, and other trade partners.
Closer ties with Washington could facilitate financial support and investment, but Argentina also relies heavily on China for trade, financing, and currency-swap arrangements.
Relations with Brazil are particularly important because Brazil is Argentina’s largest regional partner and a central market for industrial exports.
The exchange-rate debate could also affect the country’s role in Mercosur. A heavily managed or overvalued peso may weaken Argentine exports, while a sharp depreciation could produce tensions with neighboring economies.
The 2027 presidential election will intensify these pressures. The government may want to avoid a major devaluation before voters go to the polls, while economists and investors may demand an adjustment before the imbalance becomes more dangerous.
That political timing is one reason Gopinath and Gómez Minujín have emphasized reserves and exchange-rate flexibility.
A government that delays adjustment may preserve short-term calm but risk a more abrupt correction later. A government that allows depreciation now may strengthen reserves but face political backlash from households already struggling with high living costs.
The increase in Argentina country risk reflects that unresolved dilemma. Markets are asking whether the current economic program can deliver growth, reserves, debt sustainability, and political stability at the same time.
The answer will depend on several variables: global interest rates, agricultural and energy exports, reserve accumulation, inflation, public support, and the government’s negotiations with creditors.
For now, Argentina remains committed to fiscal discipline, but investors are demanding greater clarity on currency policy.
The rise to 610 points—and the intraday peak of 628—shows that confidence remains fragile. The government’s return to international credit markets may take longer than officials originally expected.
From teleSUR English via This RSS Feed.